Skip to content
ALL CREDIT SCORES CONSIDERED

Bad Credit
Car Finance

Been turned down before, have a CCJ, a default or no credit history. We search a panel of lenders for options that may suit your circumstances, and the initial eligibility check is a soft search.

CCJs, defaults and low scores considered.
Check eligibility with no impact on your score.

Soft search · No impact on your credit score
Finance any car
FCA regulated
No deposit needed
Excellent ★ Trustpilot
★ ★ ★ ★ ★
Driver with bad credit car finance options from CarFinanced
CCJs considered Defaults considered IVAs considered
Finance any car Explore suitable finance options
FCA regulated FRN 1014460
No deposit needed Options may be available subject to status
Excellent ★ Trustpilot
★ ★ ★ ★ ★
View CarFinanced reviews on Trustpilot
Bad credit explained

Can I get car finance with bad credit?

Yes, it is often possible. As a broker we work with specialist lenders who look at more than your credit score, so bad credit on its own does not automatically rule out a car finance agreement.

Lenders weigh your current income, what you can afford today, and your overall circumstances alongside your history. We check what may be available with a soft eligibility search, which leaves no mark on your credit file at that stage. See the finance glossary

Soft search first

The initial eligibility check leaves no mark on your credit file at that stage, so you can see what may be available before taking anything further.

No impact on your credit score

Specialist lender panel

We search a panel that includes lenders built around applicants with adverse credit, so a wider range of circumstances is considered alongside your score.

Your circumstances, not just a number
Credit terms

What counts as bad credit?

Bad credit is a general label, not a single thing. Lenders look at the markers on your file, how recent they are, and how they compare with your income today.

Credit score

A number from each credit reference agency, scored on a different scale, so one score on its own is a guide rather than a verdict.

Experian, Equifax, TransUnion

Adverse markers

CCJs, defaults, IVAs and missed payments all count as adverse markers. Each one is weighed alongside your current circumstances.

Most drop off after six years

Affordability

Lenders check that monthly payments fit your income after rent, bills and other regular commitments. This is a Consumer Duty requirement.

Income and expenditure assessed

Recent activity

On-time payments across the last twelve months carry real weight, even when older markers remain on your file.

Recency matters

Deposit (optional)

A deposit is not required, but one you can afford often widens the options a lender will offer and lowers the monthly payment.

Lowers what you borrow

What affects your car finance approval?

Lenders check three things. Whether you can afford the monthly payment today, whether your income is reliable, and whether the amount and term you have asked for fit your circumstances. Credit history is one part of that picture.

Specialist lenders in our panel are built around assessing the whole picture, which is why a soft eligibility check with us often returns options even when a high street lender has not. The soft search leaves no mark on your credit file at that stage.

What a lender looks for

✓ Affordability today, not only history
✓ On-time payments in the last 12 months
✓ Realistic amount for the term you choose
A rough monthly figure

What might it cost?

Move the controls to a borrowing amount, a term and a credit rating that feel close to yours. The figure on the right updates as you change it. It is a picture, not a quote.

Your figures

Finance type
£8,000
£1,000 – £50,000
Over how many months?
What’s your credit rating like?

Example Hire Purchase APRs: Bad 19.9% · Average 14.9% · Good 9.9% · Excellent 7.9%. Actual rates depend on eligibility and lender assessment.

The honest trade-off

Worth doing, with your eyes open.

Bad credit car finance can get you back on the road and help you rebuild your file at the same time. It also costs more than a prime borrower pays. Both of those are true. Here is each side laid out so you can weigh them before you apply.

The upside

What you gain

  • Rebuild your credit as you pay. Every on-time monthly payment is reported to the three credit reference agencies, so your file improves month by month.
  • Fixed monthly payment for the whole term. You know the figure on day one and it does not change, which makes a household budget easier to run.
  • A car you own at the end on HP. The final payment transfers ownership to you. On PCP you keep the choice to hand back, part-exchange or buy.
  • Soft eligibility check first. You can see what you are likely to be offered before you apply, with no mark left on your credit file at that stage.
  • The whole picture, not only the score. Specialist lenders look at affordability today and the last 12 months of on-time payments, not only your history.
The trade-off

What to weigh

  • Higher APR than a prime borrower pays. Specialist lenders price in the extra risk. A better file in future means a better rate when you refinance or buy again.
  • Total cost of credit is higher over the term. A longer term lowers the monthly figure but raises the total you pay. The calculator above shows both numbers side by side.
  • The car is security for the loan. Missed payments can lead to the car being repossessed, and arrears are recorded on your file.
  • Smaller lender panel than prime. Fewer specialist lenders means fewer deals to compare, so the first offer is not always the strongest fit.
  • Rebuilding your file takes months, not weeks. A short run of on-time payments helps a little. A year or more makes a real difference to your next application.

All finance is subject to status, affordability and the lender’s assessment. Missing payments can lead to additional charges and loss of the vehicle.

Improve your chances

Give your application a better shot.

Six things that genuinely help, inside your control. Tick the ones you have done (or will do) and the readiness panel on the right updates. Nothing here is a credit decision, it is a picture of how ready an application is likely to feel.

A general readiness guide, not a credit decision. All finance is subject to status, affordability and the lender’s assessment.

What CarFinanced does

How CarFinanced arranges bad credit car finance.
Customer checking bad credit car finance eligibility on a laptop
Step one

Check your eligibility

You give us a few details about yourself and the finance you are looking for. This initial eligibility check is a soft search, so it leaves no mark on your credit file at that stage.
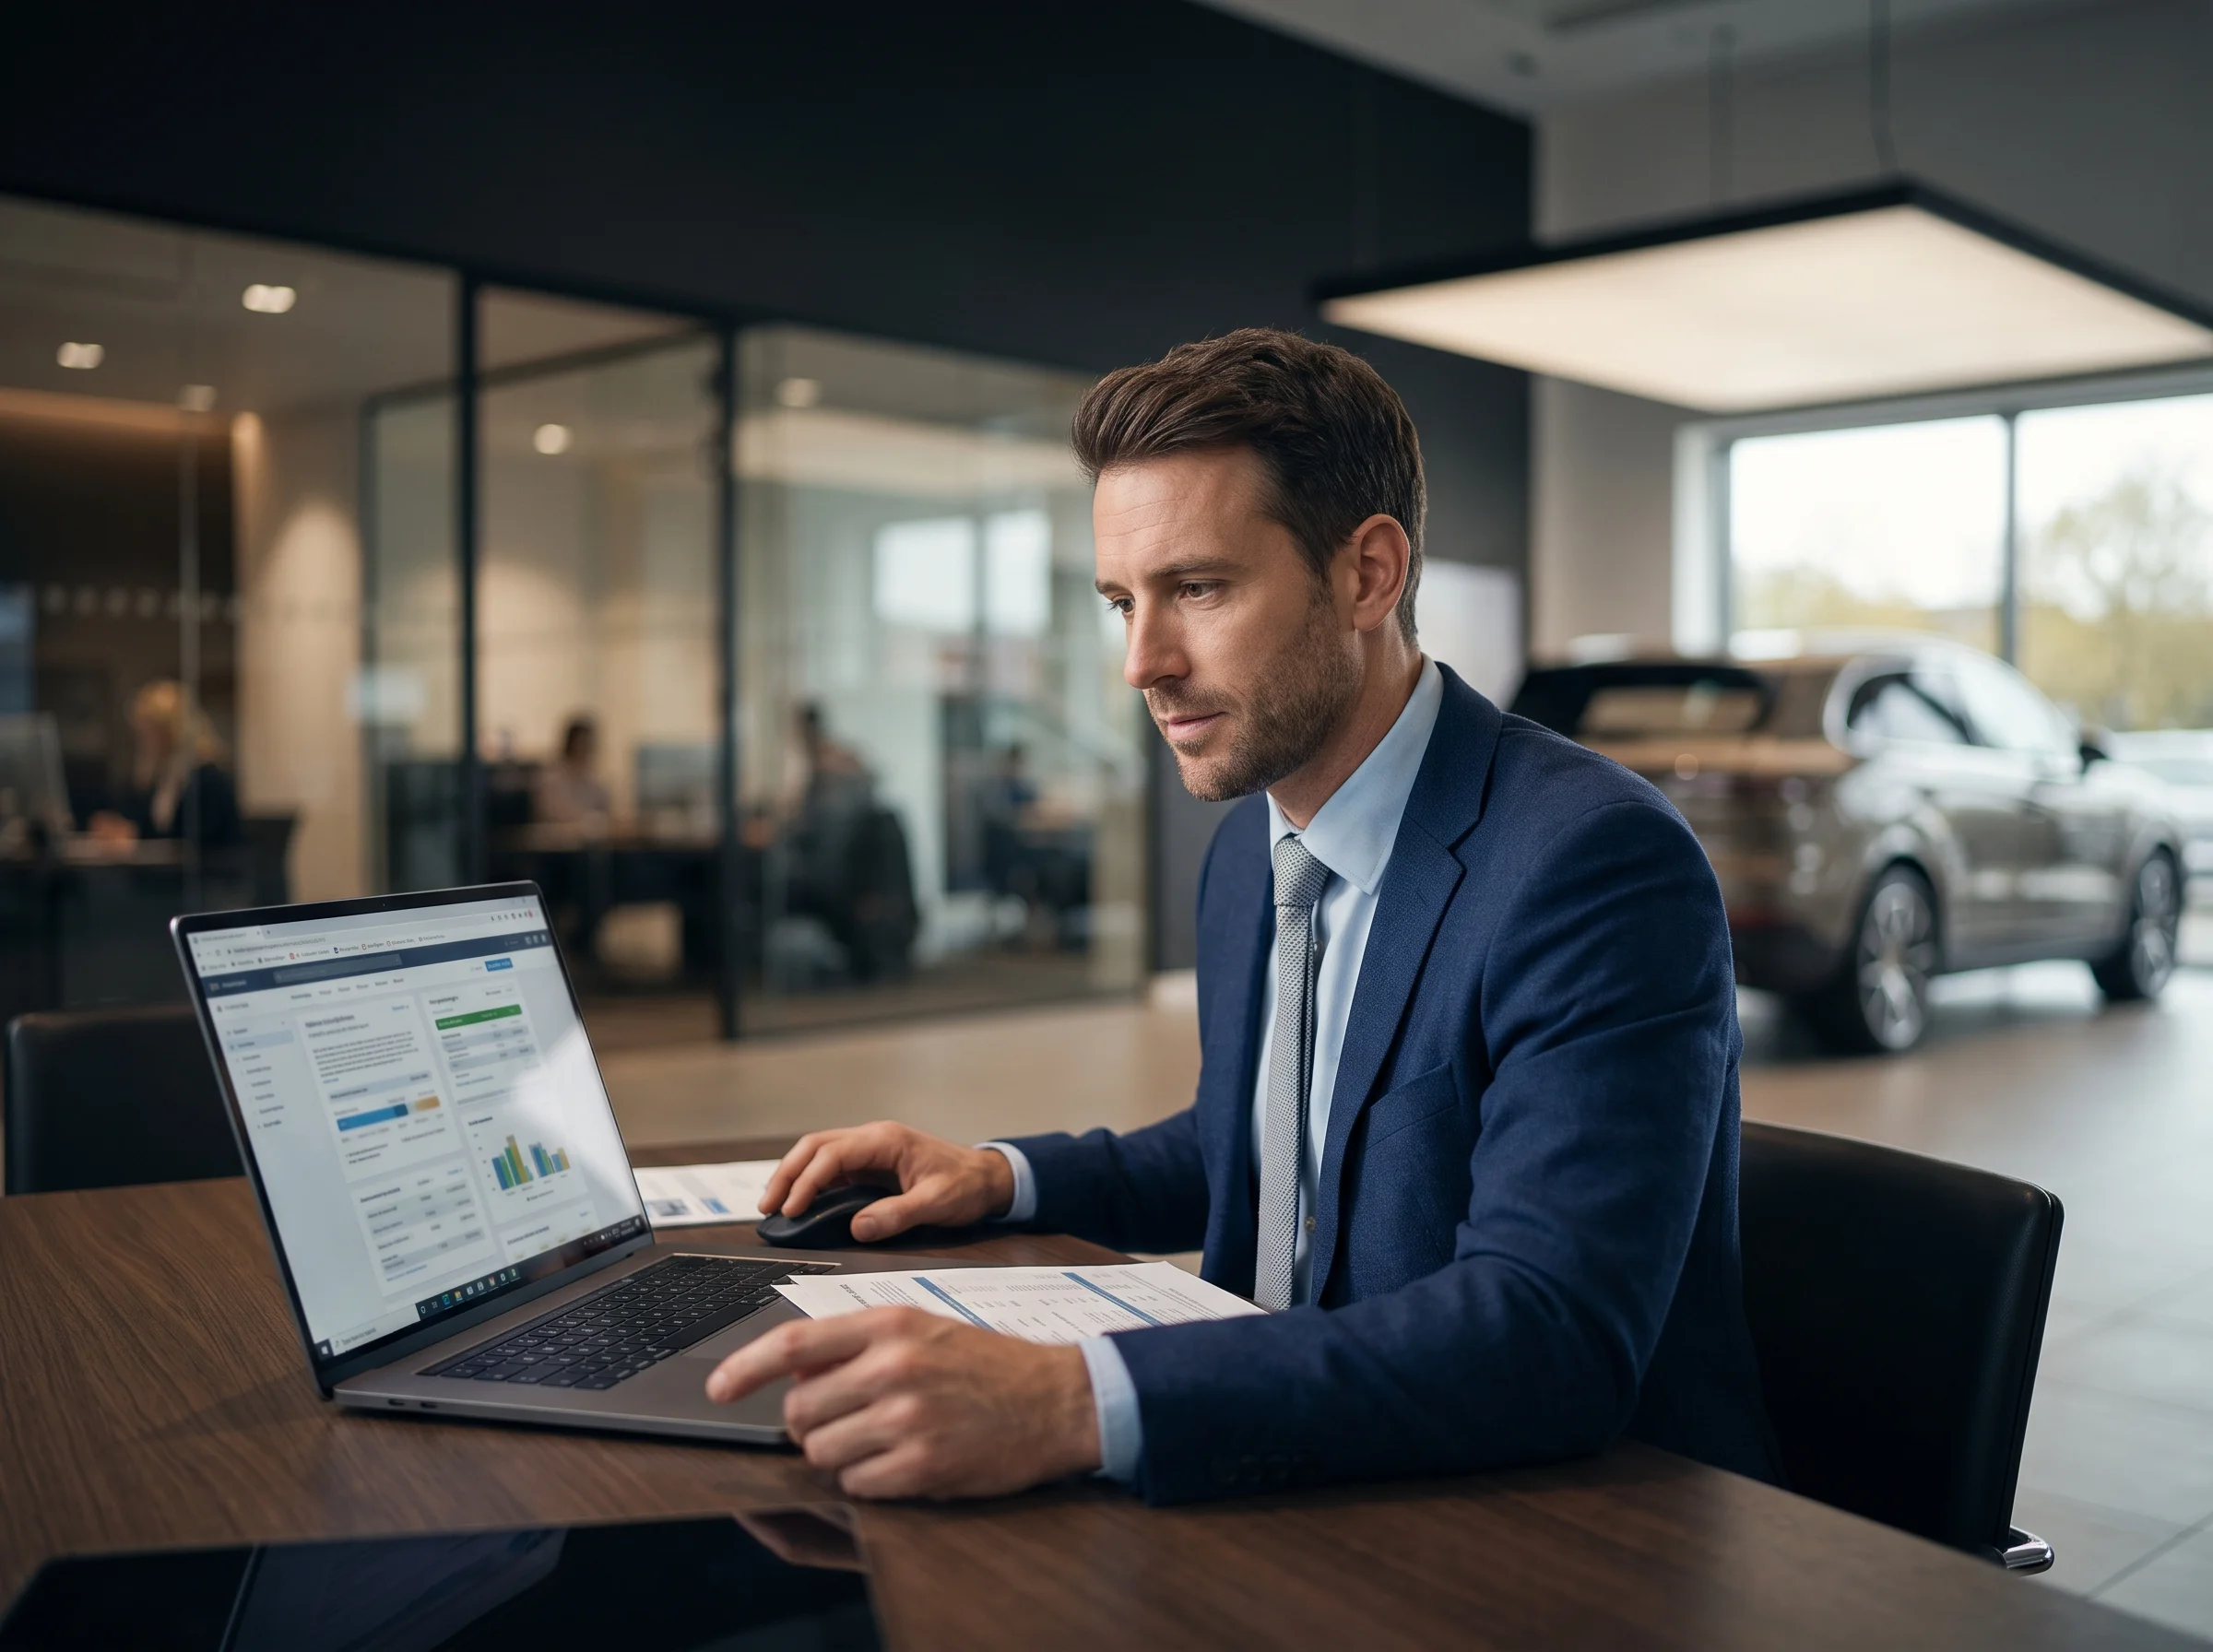
Credit broker comparing bad credit car finance options from a panel of specialist lenders
Step two

We search our specialist panel

We look for the best rate from our panel of lenders built around credit-impaired applications, and offer you the best deal you are eligible for. We do not give advice or a recommendation, so the decision stays with you.
Customer signing a bad credit car finance agreement with a broker
Step three

Complete your agreement

All finance is subject to status and income, and applicants must be 18 or over. Depending on the supply route of your vehicle, a separate administration fee of £299 may apply.

Check Your Eligibility

Soft search · No impact on your credit score

Pick your fit

HP or PCP, which fits bad credit?

Two routes to the same car, with real differences in the monthly figure, the deposit, and what happens at the end of the term. Each option is spelled out below, with a side-by-side table underneath that lines up the detail at a glance.

Option 1

Hire Purchase

Pay the car off in equal monthly payments. On the final payment, the car is yours. The simpler of the two routes and the one with the wider lender panel when credit is impaired.

Best if you want to keep the car Panel wider on bad credit
Read the Hire Purchase guide
Option 2

Personal Contract Purchase

A deferred final payment keeps the monthly figure lower across the term. When it ends, you either hand the car back, swap it on a part-exchange, or settle the balloon to keep it. Fewer lenders write PCP for applicants with impaired credit, so expect a tighter panel on this route.

Best if you like changing cars often Panel narrower on bad credit
Read the PCP guide

Side-by-side detail

Six questions people ask when choosing between the two.

Aspect Hire Purchase PCP
Monthly payment Higher, because you repay the full car value Lower, because part is deferred to the end
Deposit Optional on many agreements Usually required, often 10% or more
At the end of the term Final payment transfers ownership to you Hand back, part-exchange, or pay the balloon
Mileage limit No mileage limit Annual limit agreed up front, excess charged
Who owns the car Lender until final payment, then you Lender throughout, you only after the balloon
Bad credit availability Wider lender panel, more flexible Narrower, PCP depends on residual value models

Which should you pick?

If you want to own the car outright

Pick Hire Purchase. Every monthly payment chips the balance down, the car is yours on the final one, and there is no mileage limit to worry about on the way.

If a lower monthly matters most

Pick PCP, if your credit is up to it. The deferred balloon brings the monthly down, and at the end you choose whether to keep, swap or hand the car back.

Not sure which the panel will approve? The eligibility check returns a decision for both routes at once, with no footprint on your file.

Check eligibility for both
Soft search · No impact on your credit score
Why CarFinanced

Why drivers use CarFinanced for bad credit car finance.
Car finance adviser reviewing an application 01

FCA regulated

CarFinanced Ltd is authorised and regulated by the Financial Conduct Authority under firm reference number 1014460. Our authorisation can be checked on the public FCA register.

Car finance broker comparing finance options 02

A broker, not a lender

We do not lend. We search our panel of lenders and offer you the best deal you are eligible for. The lender pays us a commission, a fixed fee or a fixed percentage of the amount borrowed, which does not influence your rate.

Customer checking car finance eligibility 03

A soft eligibility check

The initial eligibility check is a soft search, so it leaves no impact on your credit score at that stage. You can see what may be available to you before taking anything further.
Cost breakdown

What makes up a bad credit car finance payment?

Five things decide what you pay each month. Knowing how they interact makes it easier to work out what fits your budget before you apply.

Vehicle price

The agreed price of the car. Take off any deposit and what is left is the amount you finance.

Sets the starting point

Deposit

Optional on most agreements. Putting more down reduces the amount financed, which lowers the monthly payment and the total cost of credit.

Lowers what you borrow

Interest, shown as APR

Specialist lenders typically price inside a 9.9% to 39.9% APR band for bad credit, depending on your file and affordability. Your own rate is set by the lender.

Subject to status

Agreement term

The number of months you repay over. A longer term lowers the monthly payment but raises the total you pay. The calculator above shows both.

Changes the monthly and the total

Your credit profile

How your file reads: income, outgoings, any markers and on-time payments in the last 12 months. It shapes which lender fits and at what rate.

The whole picture, not only the score
Customer stories

Making car finance simple for 10,000+ customers

★★★★★
Excellent Trustpilot ↗
★★★★★
“I’ve bought many cars using finance companies in the past but none have been as good as CarFinanced. Special thanks for overseeing the process and ensuring I got the best deal on my new car.”
Mike Davis Happy customer
★★★★★
“Quick, simple process. My account manager was great throughout. Very helpful, professional and quick with responses to any questions I had.”
Kirsty Baillie Happy customer
★★★★★
“CarFinanced explained the finance agreement in detail, which gave us confidence to move forward with the car.”
Samuel Morrison Happy customer
★★★★★
“Thank you CarFinanced. I applied and picked up my car within a few hours. Outstanding service from all the team.”
Mohammed Jamal Happy customer
★★★★★
“Excellent service from start to finish. Everything was explained clearly and my questions were answered efficiently.”
Lisa Smith Happy customer
★★★★★
“Excellent service. The team arranged the finance quickly and remained very responsive throughout the process.”
Basra Nori Happy customer
★★★★★
“My account manager was absolutely first class. Patient, knowledgeable and nothing was too much trouble.”
Martyn Pearce Happy customer
★★★★★
“Fantastic service. Very professional and polite, making the whole experience straightforward from beginning to end.”
Richard Dixon Happy customer
01 What credit score do I need for car finance?

There is no single minimum. Each lender sets its own threshold and weighs it against your income, outgoings and payment history. Specialist lenders on CarFinanced’s panel accept scores where high street lenders decline, because they look at the full picture of affordability. All finance is subject to status and the lender’s assessment.

02 Can I get car finance with a CCJ?

Often yes. A County Court Judgment stays on your file for six years and is weighed alongside your current income and payment history. A CCJ paid in full within one calendar month of judgment is removed from the register entirely. Subject to status and the lender’s assessment.

Full CCJ car finance guide →
03 Can I get car finance with a default?

Often yes. A default stays on your file for six years from the date it was recorded, settled or not. Specialist lenders weigh how old it is, whether it was cleared, and your on-time payments in the months since. Subject to status and the lender’s assessment of your full picture.

Defaults car finance guide →
04 Can I get car finance after an IVA?

Yes, often. Many specialist lenders consider you once your IVA is active with payments up to date, and more will consider you once it has been discharged. You may need written permission from your insolvency practitioner first. Subject to status and the lender’s affordability assessment.

IVA car finance guide →
05 Can I get car finance with no credit history?

Yes, often. A thin or empty file means a lender has less to weigh, not something negative to penalise. Specialist lenders look at your income, employment, address and bank conduct to build a picture. First-time borrowers are a core audience. Subject to status and the lender’s assessment.

No credit history guide →
06 Will checking my eligibility hurt my credit score?

No. The CarFinanced eligibility check is a soft search, visible only to you and the searching lender, so it leaves no mark on your credit file. A hard search only happens if you accept an offer and formally apply to a lender, which you decide to do. Nothing is marked while you decide.

07 Can I get bad credit car finance with no deposit?

Often yes. A deposit is not required on most applications, though putting one down lowers the monthly payment and the total cost of credit. A part-exchange counts as a deposit when the car has equity. Approval is subject to status and the lender’s affordability assessment.

No deposit car finance →
08 Is “guaranteed” bad credit car finance real?

No. UK consumer credit rules require every lender to assess affordability on each application, so no broker or lender can guarantee acceptance in advance. Anyone promising that is misleading you. What CarFinanced can offer is a soft check that shows likely options. Subject to status.

Guaranteed car finance explainer →
09 Can I get car finance if I have been refused before?

Often yes. A previous refusal is one lender’s decision, not every lender’s, and the refusal itself is not recorded on your file (only the search is). Specialist lenders may still consider your application. Spacing hard applications a few months apart helps. Subject to status and the lender’s assessment.

Refused car finance guide →
10 Can I settle a bad credit car finance agreement early?

Yes. Under the Consumer Credit Act 1974 you can request an early settlement figure at any time, and the lender must provide it within 28 days. Voluntary termination rights may also apply once you have paid at least half the total amount payable. Terms are set in your agreement.

Early settlement guide →

Ready to see your bad credit car finance options?

Start with a soft eligibility check and see what may be available based on your circumstances.
Soft search with no impact on your credit score at this stage. Finance is subject to status and affordability. Applicants must be 18 or over. CarFinanced is a credit broker, not a lender. FCA FRN 1014460.